

Jason and Grace Tan, both 48, earn $7,500 and $6,000 a month. Their net worth tracker shows $900,000: $200,000 in cash and investments and $700,000 in the Central Provident Fund (CPF), much of it in the Ordinary Account and already committed to their flat. When Jason's colleague Farid, also 48, says his household's $900,000 is enough to stop working this year, the Tans ask whether theirs is too.
CPF savings belong to the member, and they belong in a net worth statement. CPF holds them in separate accounts, though, and each account has its own rules on what the money can pay for and from what age.
Split by those rules, the Tans can spend $200,000 (about 22% of their total) before 55. Farid's household holds $700,000 in cash and investments and can spend all of it from the day it stops. The sections below sort the Tans' $900,000 into four kinds of money, with the 2026 CPF figures that apply to each, and work out when they can stop.
Why Does One Net Worth Figure Mislead?
On a net worth statement the two households look identical. Splitting them by the account rules gives a very different picture:
| Kind of money | Household A (Farid) | Household B (the Tans) |
|---|---|---|
| Accessible (cash and investments) | $700,000 | $200,000 |
| Restricted retirement (SA, RA) | $55,000 | $205,000 |
| Housing-linked (OA) | $110,000 | $420,000 |
| Healthcare (MediSave) | $35,000 | $75,000 |
| Total | $900,000 | $900,000 |
Source: Illustrative figures
The CPF split in this table is an illustration. Each household's own figures are on its CPF statement.
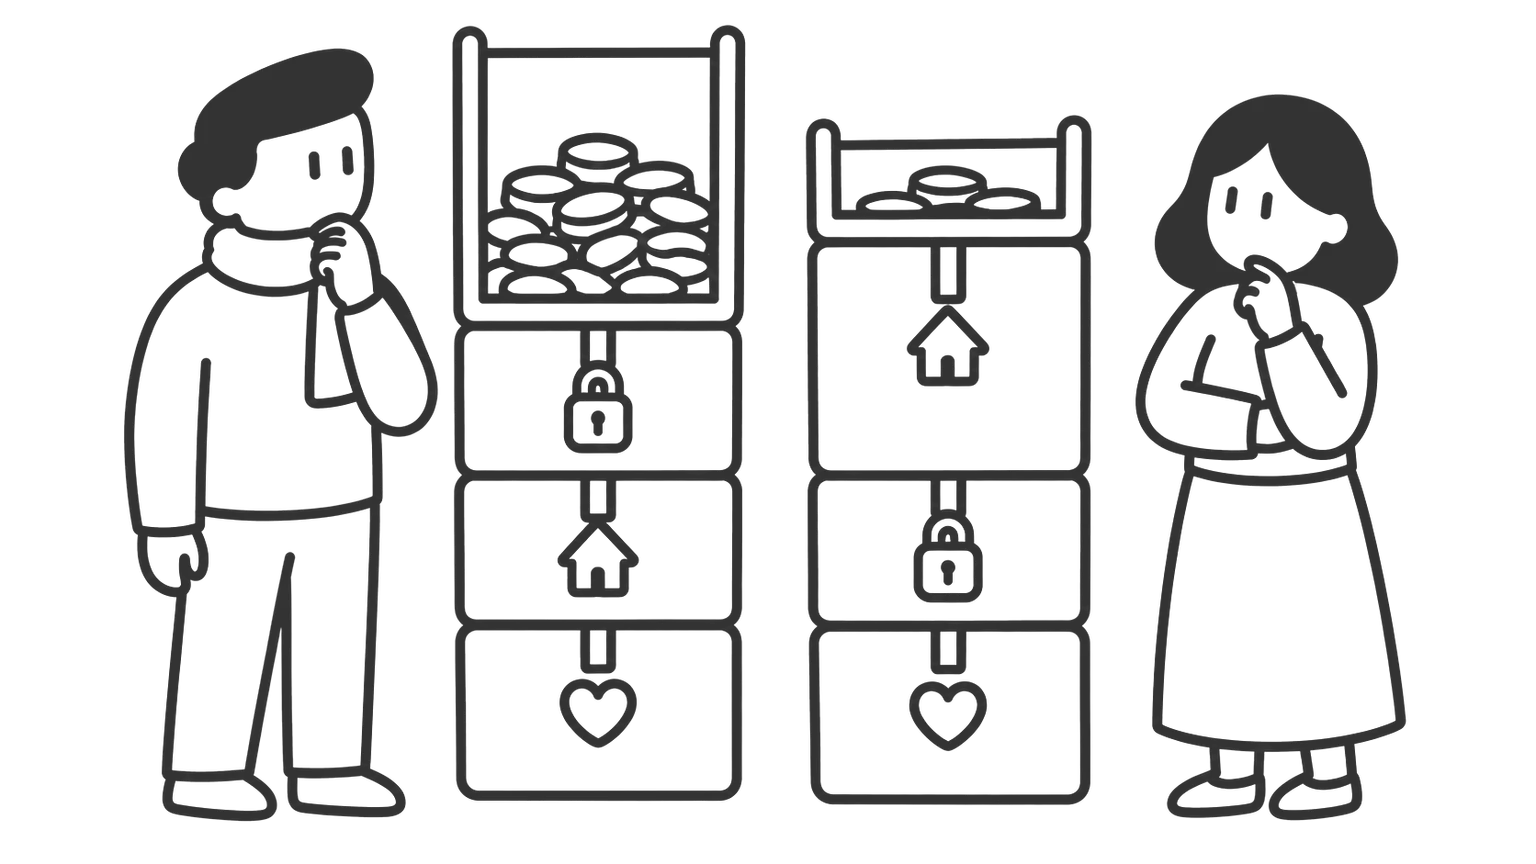
Of the Tans' $700,000 in CPF, $420,000 is in the Ordinary Account and $75,000 is in MediSave. Only the $200,000 in the first row can pay for their spending next year.
How Much Do Their CPF Savings Earn While Locked?
CPF savings earn interest while they are locked. According to the CPF Board (checked 27 September 2026), the rates from 1 October to 31 December 2026 are:
| Account | Interest rate a year |
|---|---|
| Ordinary Account | 2.5% |
| Special, MediSave and Retirement Accounts | 4% |
Source: CPF Board
The 4% floor on the Special, MediSave and Retirement Accounts has been extended to 31 December 2027 (checked 27 September 2026). The Tans' $205,000 of retirement savings earns at least $205,000 × 4% = $8,200 a year. None of that interest can pay for spending before 55.
Read Also: CPF Accounts Explained: OA, SA, MediSave And RA In 2026
What Can They Spend Before 55?
Accessible money is cash, bank deposits and investments held outside CPF. A household can spend it now, on anything.
It is the only money that pays for the years between the last pay cheque and 55. For the Tans that is $200,000. For Farid's household it is $700,000.
When Is Their Retirement Money Released?
Restricted retirement money is the Special Account, the Retirement Account and the Supplementary Retirement Scheme (SRS). Each is released at a stated age and not before.
At 55, the Special Account closes and its savings move into a new Retirement Account, together with Ordinary Account savings, up to the member's Full Retirement Sum. The sums are fixed by the year a member turns 55, according to the CPF Board's pages on the Basic Retirement Sum and the Full Retirement Sum (both checked 27 September 2026):
| Year turning 55 | Basic Retirement Sum | Full Retirement Sum |
|---|---|---|
| 2025 | $106,500 | $213,000 |
| 2026 | $110,200 | $220,400 |
| 2027 | $114,100 | $228,200 |
Source: CPF Board
The Tans turn 55 in 2033, and the CPF Board has not yet published the sums for that year. The Retirement Account pays the CPF LIFE premium, and payouts start at 65. A member who turns 55 in 2026 with $220,400 in the Retirement Account can expect about $1,780 a month from 65 on the Standard Plan (CPF Board, checked 27 September 2026). For Jason and Grace, that income counts towards their plan from 65, in whichever year they stop working.
Read Also: BRS, FRS And ERS: What CPF Members Can Withdraw At 55 In 2026
Can They Draw On The Ordinary Account And The Flat?
Housing-linked money is Ordinary Account savings. Most households use them for the down payment and instalments on a flat, and the flat's equity sits in the same group.
The money belongs to the household, but a household that lives in the flat cannot spend its equity without moving out. For the Tans, $420,000 of their $900,000 falls in this group. It counts in their long-term picture and stays out of the near-term one.
Where Does Their MediSave Fit?
Healthcare-restricted money is MediSave. Members can use it at any age for hospital bills, approved outpatient treatment and health insurance premiums, and for nothing else.
MediSave has its own cap. The CPF Board raised the Basic Healthcare Sum for members below 65 from $75,500 to $79,000 for 2026 (checked 27 September 2026). A member who reaches 65 in 2026 keeps $79,000 as the fixed figure from then on. The Tans' $75,000 of MediSave never becomes spending money, so they keep it out of the figure they use to decide when to stop working.
How Long Would $200,000 Last From 48?
The split changes their emergency fund first. A large CPF balance with three weeks of cash is still three weeks of protection, because CPF cannot pay next month's rent.
It also changes the stopping date. The Tans spend $5,000 a month, or $60,000 a year, and the seven years from 48 to 55 need 7 × $60,000 = $420,000. Their $200,000 runs out after about three years and four months, before any investment returns. Farid's $700,000 covers the same seven years and leaves $280,000.
Read Also: Can You Retire Before 55 In Singapore?
Read Also: See Your CPF Balances Alongside Your Retirement Plan In Cashmere Pocket
When Can The Tans Stop Working?
After employee CPF contributions of 20%, Jason takes home $6,000 and Grace $4,800, so the household brings home $10,800 a month. They save the $5,800 left after spending, or $69,600 a year. Two more years of work takes their accessible money to $200,000 + (2 × $69,600) = $339,200 before returns, and the five years from 50 to 55 need 5 × $60,000 = $300,000. They set their stopping date at 50, with retirement savings and CPF LIFE for the years after 55 and MediSave kept for healthcare.
A net worth figure that includes every CPF dollar suits a household measuring its long-term wealth, as the Tans' $900,000 does. A household deciding when it can stop working needs the four-way split instead. The split is one way to read CPF balances and is not a rule from the CPF Board, and some households count housing equity differently, for example by counting the gain from a planned downgrade. The account rules behind each group are the CPF Board's, and the figures above apply to members turning 55 between 2025 and 2027.